Strap in and rev your engines because we’re about to take you on a road trip through the world of auto insurance in Massachusetts. Whether you’re a seasoned driver or just setting out on your first solo ride, understanding the ins and outs of car insurance could save you big bucks. So, buckle up and let’s explore how to protect yourself and your vehicle without breaking the bank!
In Massachusetts, the auto insurance landscape can feel like navigating Boston’s intricate street grid—complex but manageable with the right roadmap. From dissecting the mandatory coverage levels to exploring optional add-ons that might just be your saving grace in a pinch, we’ve got the full breakdown ready for you. Let’s dive into how much it costs and what you can do to keep those premiums in check.
Understanding Auto Insurance Coverage in Massachusetts
Did you know that Massachusetts drivers pay an average of $1,223 per year for auto insurance? That’s a chunk of change! But understanding what you’re paying for is crucial.
Let’s break down the types of auto insurance coverage you can get in Massachusetts. Knowing your options can save you money and give you peace of mind.
Types of Auto Insurance Coverage Available
Massachusetts drivers are required to carry several types of insurance. Liability coverage is a must. It covers bodily injury and property damage to others if you’re at fault. But that’s just the beginning.
- Bodily Injury Liability: Covers costs if you hurt someone in an accident.
- Property Damage Liability: Pays for damage you cause to someone else’s property.
- Personal Injury Protection (PIP): Covers medical expenses, regardless of who’s at fault.
- Uninsured Motorist Coverage: Protects you if the other driver doesn’t have insurance.
State Minimum Insurance Requirements
Massachusetts has specific minimums, and you’ll want to meet these to stay legal. Here’s what you need:
Bodily Injury: $20,000 per person, $40,000 per accident.
Property Damage: $5,000 per accident.
But don’t stop there! These figures are just the legal floor. Consider increasing your coverage to protect yourself fully.
Optional Coverages and Their Benefits
Massachusetts offers several optional coverages that can be lifesavers. For instance, Collision coverage pays for damage to your car after an accident, while Comprehensive coverage handles non-collision-related incidents like theft or weather damage.
Adding medical payments coverage is a smart move too. It covers medical costs that PIP doesn’t. And let’s not forget about rental reimbursement for when your car’s in the shop.
Pro Tip: Opt for gap insurance if you have a car loan. It covers the difference between what you owe and the car’s value if totaled.
By understanding and choosing the right coverage, you can drive with confidence. Don’t settle for the bare minimum—protect yourself and your assets!
Factors Influencing Auto Insurance Rates
Ever wondered why your car insurance bill looks like it just did a jump shot? Well, you’re not alone. Auto insurance rates in Massachusetts can vary dramatically, and it’s not just about how you drive.
Let’s dig into the nuts and bolts of what makes those numbers tick. From your driving history to the type of car you own, the factors are a mix of personal and universal.
How Driving History Impacts Insurance Costs
Your driving record is like your credit score for insurers. It’s a huge factor. If you have a track record of accidents or violations, your rates will spike faster than a caffeine high. Insurers love safe drivers. They reward them with lower rates. So, keep it clean on the road!
Here’s the deal: even a single speeding ticket can raise your premium by a significant margin. But don’t lose hope!
Pro Tip: Take a defensive driving course. Some insurers offer discounts for this, and it can offset those pesky tickets.
The Role of Vehicle Type in Insurance Rates
Think your car is just a mode of transport? Think again. The type of vehicle you drive is a biggie when it comes to insurance rates. High-end luxury cars or sports models? Expect to pay more. They’re costlier to repair and attract more theft.
But here’s the surprise: even your car’s color can influence rates in some cases. Economy sedans and SUVs often get cheaper rates. Why? They’re safer and cheaper to fix.
So before you buy that flashy new ride, consider how it’s going to affect your insurance bill. Because, yes, it will.
Average Cost of Auto Insurance
Ever wondered how much you’re shelling out for auto insurance compared to others in Massachusetts? You’re not alone. The cost of car insurance can feel like a mystery. But understanding the average rates can help you gauge if you’re getting a fair deal.
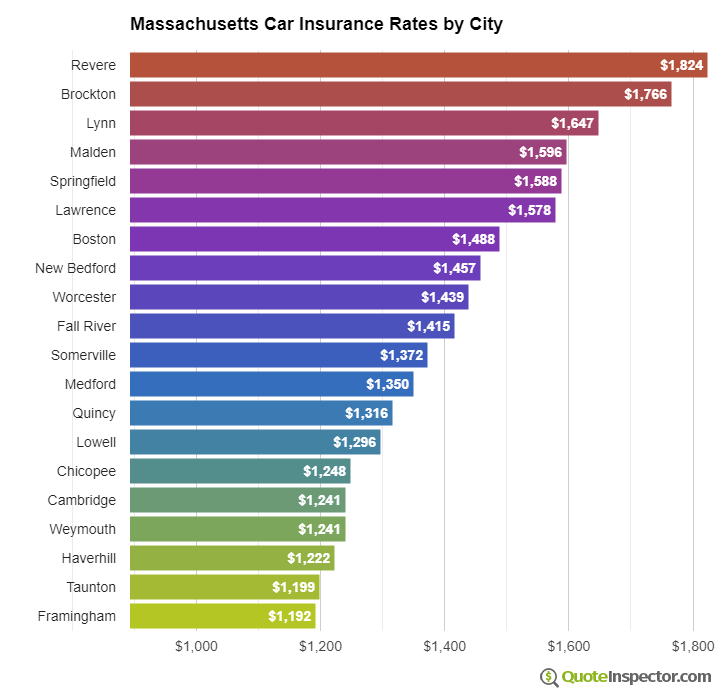
Here’s the deal: Auto insurance costs in Massachusetts are influenced by a mix of factors, but one of the biggest is where you live. Urban areas often have higher rates due to more traffic and accidents. Meanwhile, rural areas typically see lower costs.
Massachusetts Auto Insurance Cost Breakdown
Let’s dive into the numbers. This table highlights the average cost of auto insurance across different cities in Massachusetts. Notice how the location impacts the price significantly.
| City | Average Cost | Coverage Type | Provider |
|---|---|---|---|
| Boston | $1,800 | Full Coverage | Allstate |
| Worcester | $1,450 | Full Coverage | GEICO |
| Springfield | $1,300 | Liability Only | Progressive |
| Pittsfield | $1,100 | Liability Only | State Farm |
Compared to the national average of about $1,500 annually for full coverage, Massachusetts is slightly higher. The state’s urban centers, like Boston, push this average up. BUT, if you live in smaller towns like Pittsfield, you might enjoy rates closer to the national norm.
Pro Tip: If you’re in an urban area, consider bundling your insurance policies to snag a discount.
Ways to Reduce Auto Insurance Costs
Did you know that the average driver in Massachusetts spends around $1,223 annually on auto insurance? That’s a hefty chunk of change! But here’s the deal: you can actually lower your premiums with some smart strategies.
By taking the right steps, you can see significant savings on your auto insurance. Whether it’s through discounts, bundling, or other methods, the key is knowing where to look and what to ask for.
Designing Strategies to Lower Premiums
First things first, let’s talk strategy. One of the easiest ways to save is by increasing your deductible. This means you’ll pay more out of pocket in the event of a claim, but your monthly rates will drop. Another tactic? Keep your driving record clean. Insurers love safe drivers and often reward them with lower premiums.
Available Discounts from Various Insurers
Insurance companies offer a dizzying array of discounts. Are you missing out on any? Here’s a list of common ones to check:
- Good Driver Discount: Has your record been spotless for five years? Score!
- Multi-Vehicle Discount: Insure more than one car? Save big.
- Good Student Discount: Got a B average or better? Get rewarded.
- Anti-theft Device Discount: Keep your car safe, and your wallet safer.
- Low Mileage Discount: Drive less, pay less.
Pro Tip: Call your insurer and ask for a full rundown of available discounts. They might have something you’re eligible for that you didn’t even know about!
The Benefits of Bundling for Cost Savings
Ever heard of bundling? It’s like the insurance world’s secret sauce for savings. When you bundle your auto insurance with other policies (like home or renters), insurers often give you a discount. This is because it’s more convenient for them and shows your loyalty.
Let’s look at a quick comparison:
| Scenario | Monthly Cost | Annual Savings |
|---|---|---|
| Auto Insurance Only | $102 | $0 |
| Bundled with Home Insurance | $185 | $252 |
As you can see, bundling can lead to significant savings. So, if you currently have separate policies, it might be time to consider combining them.
Top Auto Insurance Providers
Choosing the right auto insurance provider can be daunting. But finding the perfect match can save you a ton of money and hassle in the long run.
In Massachusetts, certain auto insurance companies stand out from the rest due to their stellar reputation and customer-centered policies. With a focus on customer satisfaction and unique offerings, these companies can make a significant difference in your insurance experience.
Leading Auto Insurance Companies in Massachusetts
When it comes to auto insurance, not all companies are created equal. Here are some of the top-rated providers you should consider:
- Liberty Mutual
- Geico
- State Farm
- Progressive
- Allstate
These companies have a solid track record of serving Massachusetts residents with care and efficiency. But what sets them apart?
Customer Satisfaction Ratings and Reviews
Customer reviews and ratings can make or break an insurance company’s reputation. Here’s how these companies stack up in terms of customer satisfaction:
| Insurance Provider | Customer Satisfaction Rating | Notable Feedback |
|---|---|---|
| Liberty Mutual | 4.5/5 | Flexible plans and excellent customer service |
| Geico | 4.3/5 | Affordable rates and easy claims process |
| State Farm | 4.6/5 | Strong local presence and personalized service |
| Progressive | 4.4/5 | Innovative tools and comprehensive coverage |
| Allstate | 4.2/5 | Reliable support and customizable policies |
Unique Offerings from Top Providers
Each of these companies has something unique in their toolkit:
- Liberty Mutual offers accident forgiveness and new car replacement.
- Geico is known for its multi-policy discounts and mobile app convenience.
- State Farm emphasizes its network of local agents for personalized service.
- Progressive has a “Name Your Price” tool that can fit any budget.
- Allstate provides personalized alerts and a dedicated claims team.
Pro Tip: Choose a provider that best aligns with your driving habits and customer service expectations.
Legal and Regulatory Considerations
Did you know that Massachusetts has some of the strictest auto insurance laws in the United States? If you’re driving in the Bay State, understanding these laws isn’t just smart—it’s essential.
Massachusetts requires you to have auto insurance to cover both bodily injury and property damage. This isn’t optional. If you’re caught driving without it, you could face hefty fines, license suspension, or even jail time. So, what exactly do you need to know to stay on the right side of the law?
Mandatory Auto Insurance Requirements
In Massachusetts, every driver must have a minimum amount of liability coverage. This includes $20,000 per person for bodily injury, $40,000 per accident, and $5,000 for property damage. But here’s the deal: these amounts are just the minimum. Most experts recommend higher limits to fully protect your assets.
Massachusetts is a “no-fault” state, which means your insurance covers your injuries regardless of who caused the accident. You’ll need Personal Injury Protection (PIP) to cover medical expenses and lost wages up to $8,000.
Filing a Claim in Massachusetts
Getting into an accident is stressful. But filing a claim doesn’t have to be. Step #1: Notify your insurer as soon as possible after an accident. Provide all necessary details, including photos and witness information. Step #2: Your insurer will investigate and determine their liability. But be aware, Massachusetts has a comparative negligence rule, meaning your compensation could be reduced if you’re found partially at fault.
Pro Tip: Always keep a copy of your insurance policy in your car. It speeds up the claim process.
Consequences of Driving Uninsured
Driving without insurance in Massachusetts isn’t just risky—it’s illegal. If you’re caught, expect fines ranging from $500 to $5,000. Plus, your driver’s license and vehicle registration could be suspended. In some cases, you may even face jail time. It’s simple: don’t gamble with your financial future.
Here’s a quick comparison to drive the point home:
| Uninsured Fine | License Suspension | Possible Jail Time |
|---|---|---|
| $500 – $5,000 | Yes | Yes |
Stay covered and drive safe!
Last Word
As you gear up to secure the best auto insurance policy, remember that every driver’s journey is unique. By understanding the key factors that influence premiums and leveraging discounts and strategic choices, you can optimize your coverage and potentially lower your costs. So, take the wheel with confidence, knowing that you’re equipped with the knowledge to make the best insurance decisions for your needs. Stay safe, and enjoy the ride!
FAQ
What is the average cost of auto insurance in Massachusetts?
The average cost of auto insurance in Massachusetts varies by city, coverage type, and provider. Generally, it can range from $1,000 to $1,500 annually, depending on these factors.
What are the state minimum insurance requirements in Massachusetts?
Massachusetts requires a minimum coverage that includes Bodily Injury to Others, Personal Injury Protection, Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property.
How can I lower my auto insurance premiums in Massachusetts?
You can reduce your premiums by maintaining a clean driving record, choosing a car with safety features, bundling your policies, and taking advantage of discounts offered by insurers.
Does my driving history affect my auto insurance rates?
Yes, a history of accidents or traffic violations can increase your insurance rates, while a clean record may help you secure lower premiums.
Are there discounts available for Massachusetts drivers?
Yes, many insurers offer discounts for safe driving, bundling policies, having a car with anti-theft devices, and more. It’s worth inquiring with your provider to see what you qualify for.
